The International Monetary Fund (IMF) warned that global public debt should reach 100% of GDP by 2029, requiring immediate government actions to halt the increase.
© Lusa
14/10/2026
by
Lusa
Athe International Monetary Fund (IMF) lists today have warned that governments must accelerate fiscal consolidation to halt the increase in global public debt, defending tax reforms and criticizing general fuel subsidies.
At a press conference today to announce the new Monitor Fiscal Report, IMF analysts indicated that global public debt reached 94% of GDP by 2025 and should reach 100% by 2029, driven mainly by the world's largest economies.
According to the organisation, public finances in several countries face increased pressures due to increased social expenditure, defence and strategic priorities, while interest charges absorb an increasing share of state budgets.
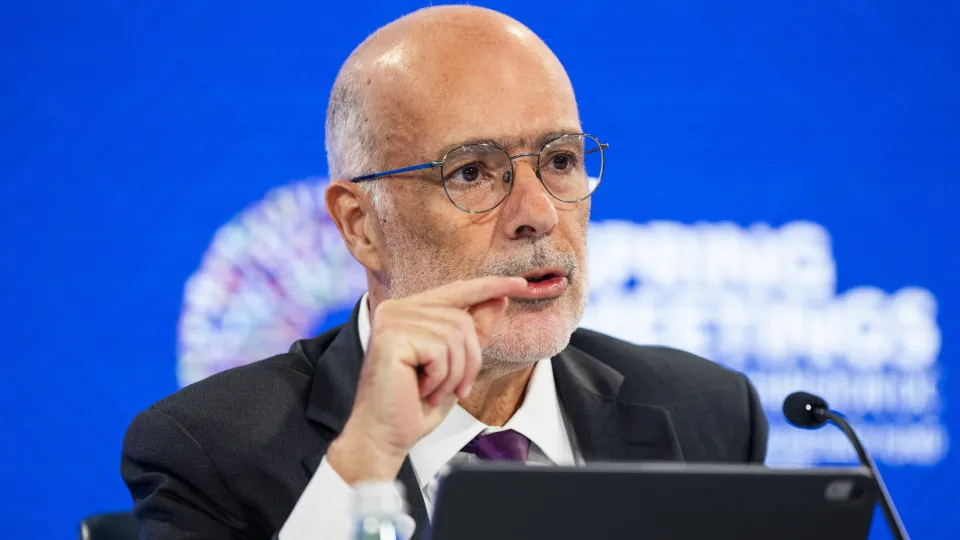
“There is little evidence of fiscal consolidation this year,” said Rodrigo Valdés, director of the Department of Budgetary Affairs of the IMF, noting that budget balances deteriorated despite stronger economic growth than expected.
“ The general message is clear. Budgetary risks are increasing and action is urgently needed in many countries,” he said.
According to the IMF, the context has become more challenging as higher interest rates make it difficult to stabilise debt. Structural changes in sovereign debt markets are also increasing vulnerability to abrupt market reassessments.
Valdés argued that countries with high levels of indebtedness should initiate adjustments before investors lose confidence.
“We don’t know where the breakpoints are, but the more expected, the greater the risk of being close to one of them,” he said. Countries, he added, need to consolidate their public accounts before markets force them to do so.”.
“Our message today is slightly different from that of the past (...) we are saying that it is urgent and that it is now, because conditions have changed,” he said.
The IMF has advocated phased fiscal consolidation plans, combined with tax reforms that increase tax efficiency rather than rely exclusively on expenditure cuts.
“ The answer essentially involves a better design of taxes at the microeconomic level, to minimize distortions,” Valdés said.
According to the Monitor Fiscal Report, reducing VAT-related distortions could generate well-being gains equivalent to up to 0.8% of GDP in emerging economies, while eliminating tax distortions that increase investment may increase GDP in the long term between 2.1% and 2.7%.
Reforms that strengthen incentives for work may also raise employment rates.
It was Dabla-Norris, Deputy Director of the Department of Budgetary Affairs, who stressed that better tax administration can boost both economic growth and public revenue.
“ Overly heavy administrative procedures can undermine business productivity and act as a tax on the growth of small and young enterprises,” he said.
The IMF estimates that countries with more effective tax administrations raise about 1.7 percentage points of additional GDP in revenue compared to those with less efficient systems.
Dabla-Norris also warned that the increase in funding costs is creating difficult choices for governments.
“ The stakes are now higher because there is less room for manoeuvre in the budgets,” he said. “As financing costs increase, the debt bill also increases.”
The IMF also renewed its criticism of the widespread subsidies for fuel and energy adopted in response to recent energy price shocks, arguing that they are costly, regressive and ineffective.
Valdés said that attempts to protect consumers from price rises this year cost between 1% and 1.5% of GDP in some countries, while on a global scale these measures represent around 1.5% of world GDP.
“ It is extremely costly from a budgetary point of view,” he said.
Instead, the IMF recommends that energy prices reflect market conditions, accompanied by temporary and targeted support for the most vulnerable households.
“ Protecting people is not the same as protecting prices,” Valdés said.